
The past six months have been a windfall for First Advantage’s shareholders. The company’s stock price has jumped 64%, hitting $19.10 per share. This was partly due to its solid quarterly results, and the performance may have investors wondering how to approach the situation.
Following the strength, is FA a buy right now? Or is the market overestimating its value? Find out in our full research report, it’s free.
Why Does First Advantage Spark Debate?
Processing over 200 million screens annually across more than 200 countries and territories, First Advantage (NASDAQ:FA) provides employment background screening, identity verification, and compliance solutions to help companies manage hiring risks.
Two Things to Like:
1. Skyrocketing Revenue Shows Strong Momentum
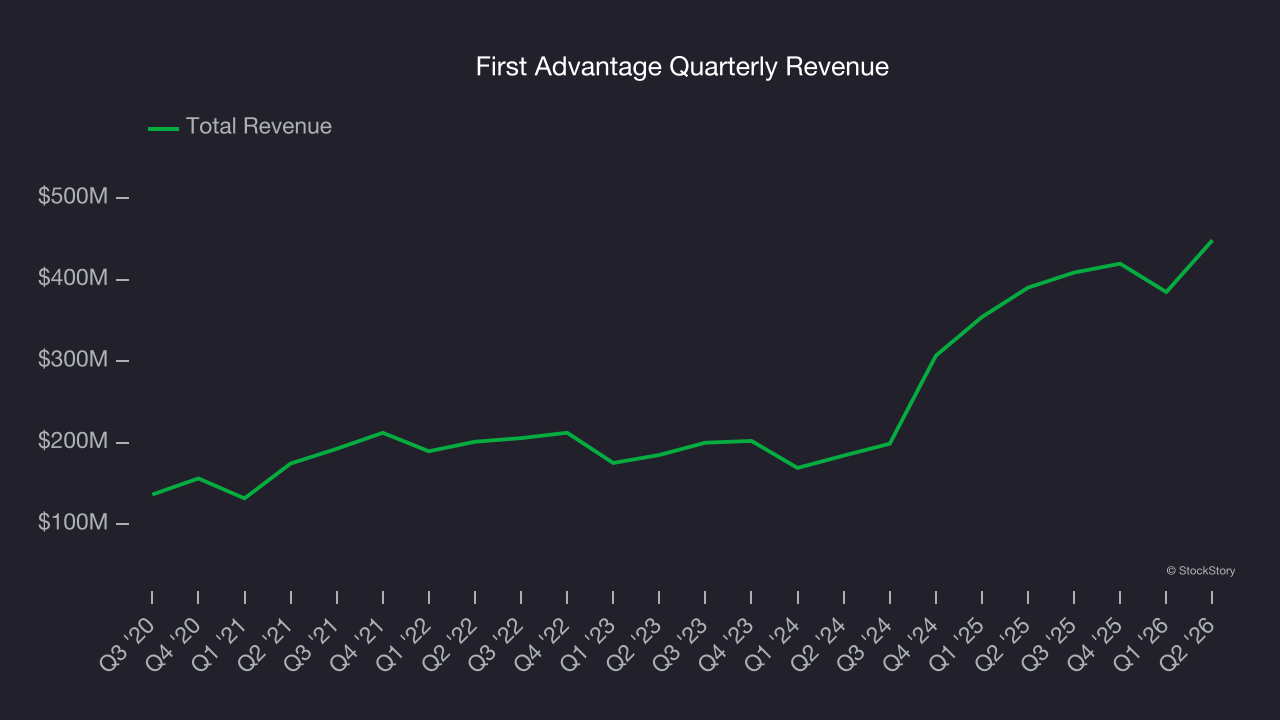
Reviewing a company’s long-term sales performance reveals insights into its quality. Any business can experience short-term success, but top-performing ones enjoy sustained growth for years. Luckily, First Advantage’s sales grew at an incredible 22.6% compounded annual growth rate over the last five years. Its growth surpassed the average business services company and shows its offerings resonate with customers.
2. Moderate Revenue Growth on the Horizon
Forecasted revenues by Wall Street analysts signal a company’s potential. Predictions may not always be accurate, but accelerating growth typically boosts valuation multiples and stock prices while slowing growth does the opposite, though some deceleration is natural as businesses become larger.
Over the next 12 months, sell-side analysts expect First Advantage’s revenue to rise by 5.5%. While this projection is below its 48.2% annualized growth rate for the past two years, it is above average for the sector and indicates the market is forecasting some success for its newer products and services.
One Reason to Be Careful:
Free Cash Flow Margin Dropping
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
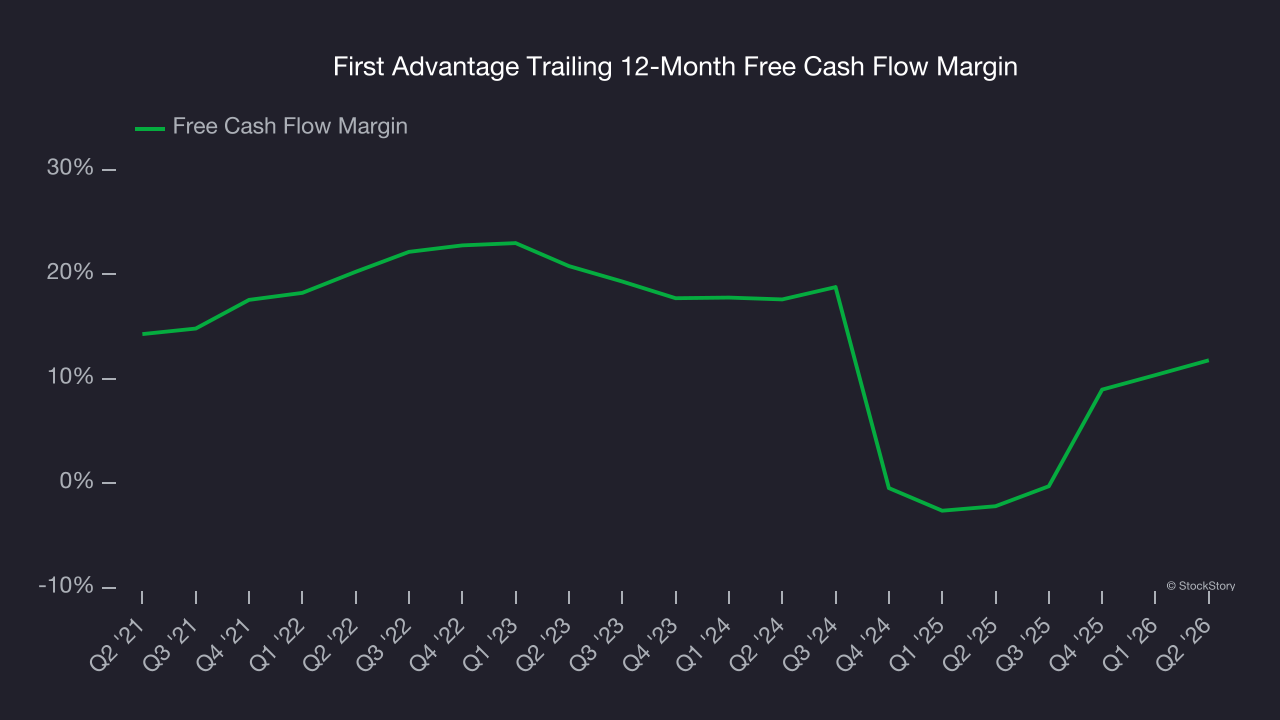
As you can see below, First Advantage’s margin dropped by 8.5 percentage points over the last five years. It may have ticked higher more recently, but shareholders are likely hoping for its margin to at least revert to its historical level. If the longer-term trend returns, it could signal increasing investment needs and capital intensity. First Advantage’s free cash flow margin for the trailing 12 months was 11.8%.
Final Judgment
First Advantage has huge potential even though it has some open questions, and with the recent rally, the stock trades at 13.9× forward P/E (or $19.10 per share). Is now the time to initiate a position? See for yourself in our in-depth research report, it’s free.
High-Quality Stocks for All Market Conditions
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.